A premium waterfront hotel could be an important addition to downtown Kelowna. It could support tourism, conferences, downtown businesses and economic activity.
But there is a separate question that deserves closer examination: should scarce municipal capital, borrowing capacity and administrative resources be exposed to commercial real estate risk when the City’s core responsibilities include roads, sewer and water systems, transportation, public safety and aging infrastructure?
That is fundamentally a question of opportunity cost, feasibility and risk.
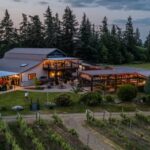
In October 2025, the City of Kelowna announced the $27.8-million acquisition of the downtown waterfront properties previously owned by Westcorp. The City stated that the acquisition was intended to be financed through the Municipal Finance Authority and that revenues from the marina, office building and parking operations would offset borrowing carrying costs while redevelopment was pursued over approximately three to five years.
The recent identification of a major hotel brand represents progress. But a hotel flag is not the same thing as a financed, constructed and economically stabilized hotel.
As someone who has worked in commercial appraisal, brokerage and investment analysis, including hotel properties, I believe major developments should be examined not only on the anticipated outcome but also on the downside case.
Hotels present distinctive risks.
A newly opened hotel does not normally achieve stabilized occupancy, room rates and operating margins immediately. Depending upon the property and market, stabilization can take several years.
Kelowna’s seasonality makes that particularly relevant. Tourism Kelowna’s 2025 statistics showed hotel occupancy of approximately 41% in January and 43% in December, compared with 87% in July and 89% in August.
A prudent feasibility analysis should therefore stress-test occupancy, average daily rate, operating expenses, financing costs and cash flow through the stabilization period.
One simple question follows:
If a new hotel requires three, four or five years after opening to achieve stabilized operations, who funds any operating shortfall?
A recognized hotel brand can provide substantial marketing, reservation and operational advantages. But branding should not be confused with assuming the underlying real estate investment risk.
There is an even more fundamental downside scenario to consider.
What if the hotel is never built?
The site has already experienced years of proposed private-sector redevelopment without construction of the contemplated hotel. That history does not establish that the City’s current strategy will fail. It does, however, make execution risk worthy of serious examination.
The City’s original announcement contemplated redevelopment over three to five years. MFA short-term financing can extend for up to five years, and some municipal borrowing structures require repayment or conversion to longer-term financing within that period.
The public should therefore understand precisely how this acquisition is financed.
What is the term? How much principal is being amortized? What amount will remain outstanding at the end of five years? If redevelopment has not occurred, will the debt be repaid, refinanced or converted to long-term borrowing? At what potential future cost?
Those are not criticisms of the project. They are ordinary investment due-diligence questions.
Municipal ownership may also have property-tax implications. Municipal property can receive statutory or permissive tax treatment, while privately occupied municipal property may remain taxable depending on the ownership and occupancy arrangement.
The complete economic analysis should therefore identify not only revenues earned from the acquired properties and borrowing costs, but also any property-tax revenue affected by municipal ownership.
Most importantly, capital has an opportunity cost.
The fact that an asset produces enough revenue to service its carrying costs does not necessarily establish that it represents the best use of municipal capital or borrowing capacity.
Private investors routinely compare expected returns against alternative investments and measure development, financing, market and operating risks before committing capital.
Municipal government should apply no lesser standard.
Governments also face a different allocation question. Private enterprise can build hotels. Only municipalities can provide many of the core services and infrastructure upon which the entire community depends.
As a current candidate for Kelowna City Council, I believe the unanswered financial aspects of this project raise legitimate questions of transparency and accountability.
Residents should be able to review the City’s business case, financing structure, independent appraisal and feasibility assumptions, current income and expenses, property-tax implications, private-sector capital contribution, risk allocation and exit strategy.
My campaign has emphasized accountable spending, transparent financial reporting and disciplined scrutiny of major capital commitments. If elected, this is the type of analysis I would bring to the Council table.
A waterfront hotel may ultimately prove to be an excellent investment in Kelowna’s downtown.
But taxpayers deserve to understand both the projected upside and the downside.
If public capital is required to make a commercial real estate development proceed where private capital previously did not, there is one fundamental question Council should be prepared to answer:
Given limited municipal resources and competing infrastructure needs, why is this the appropriate place for the City to assume investment risk?
Tim Down, CCIM, RI | Commercial Real Estate Advisor, NAI Commercial Okanagan